30+ years
advising individuals, families and business owners
Whole of market
fully independent and impartial advice
£2m cover
professional indemnity insurance per claim
Welcome
Welcome to Castle Financial Planning with me, John Castle.
I've been a financial adviser for more than 30 years, and have helped many individuals, families and business owners to successfully manage their finances. Having worked for some of the UK's largest financial service companies, I formed my own practice to focus on helping my clients achieve their financial goals.
Being independent means that I don't work for any other institutions. I work solely for my clients and in their best interests. It also means I have access to the whole marketplace and can recommend the most suitable product or service for your circumstances and needs.
The advice we provide is fully guaranteed and is backed by £2m of Professional Indemnity insurance, offering further peace of mind.
More about John and our approach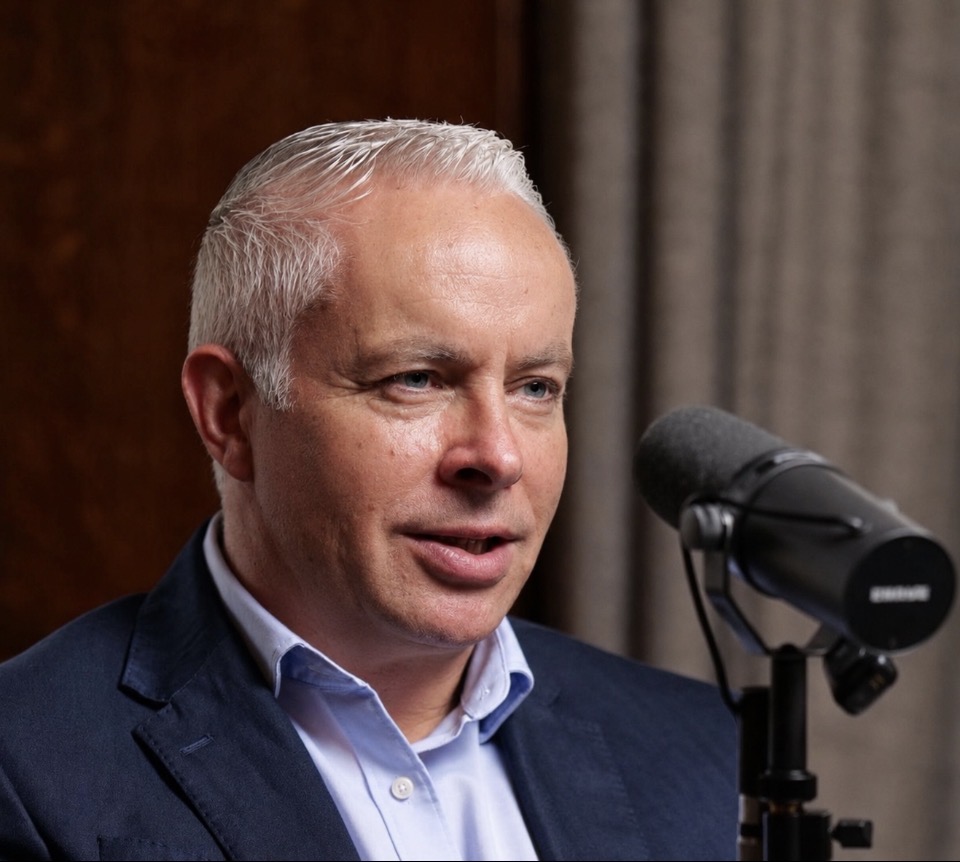
John Castle
Independent Financial Adviser, and the person you deal with from first call to annual review.
How you can benefit
Depending on your personal circumstances and needs, and where required, I will help you:
 Build an achievable financial plan
Our approach
 Protect your loved ones financially
Protecting your family
 Manage your investments effectively
Savings & investments
 Reduce your exposure to tax
Tax-efficient advice
 Secure your retirement income
Retirement planning
 Minimise your inheritance tax liability
Inheritance tax planning
Our services
Three areas
where advice makes
the biggest difference
How we add value
As your adviser, I will
Seven things that, over time, make a measurable difference to what your money does for you.
Insights
Guides on the questions clients ask most
Your peace of mind
Independent advice, inside a framework built for your protection
Being independent means that my recommendations are always based on having completed a comprehensive and fair analysis of the whole market. In addition, I subscribe to and abide by a number of laws and regulations that exist for your protection, confidentiality and security.
The Financial Conduct Authority
Our regulator, who ensures a healthy and successful financial system, so consumers get a fair deal.
The Financial Services Compensation Scheme
For your financial security, protecting customers of financial services firms that have failed, providing support and compensation.
The General Data Protection Regulation
For the protection of your data, covering EU privacy law and human rights law.
The Financial Ombudsman Service
An independent and impartial body to help resolve complaints between financial businesses and their customers.
What our clients say
Read all reviews{{ q.title }}
{{ q.body }}
Complaints process
My job is to ensure that you are delighted with the service I provide throughout our dealings.
However, should you ever feel the need to make a complaint, you can do so in accordance with our complaints procedure.
About us
One adviser, working solely for you
I formed Castle Financial Planning after three decades inside some of the UK's largest financial services companies, so that my advice would answer to one person only: the client in front of me.
Our approach
I'll take the time to get to know you and understand the things that matter most to you, including your plans and hopes for the future, as well as any concerns you may have. Then we'll review your current financial position and to what extent your finances are in alignment with the things you want to achieve.
Wherever you may need it, I'll provide you with clear and sound advice to help you build, manage and protect your wealth. By working together, we will ensure your financial plan is in good shape and working optimally for you, bringing you confidence, reassurance and peace of mind.
My commitment to you
I'm committed to providing you with the highest standards of financial advice and service. At all times, I will:
Consumer Duty
Helping you achieve good financial outcomes
As a client of Castle Financial Planning, we will provide you with the highest standards of care and support to help you achieve your financial goals. John will take the time to get to know you and understand the things that matter most to you. Beyond this, and in keeping with the FCA's 'Consumer Duty', he will:
Our advice is guaranteed
The independent financial advice we provide is fully guaranteed by New Leaf Distribution Ltd. We also carry professional indemnity insurance with a maximum claims limit of £2m per claim.
Why pensions belong in your retirement planning
Pensions are not the only way of providing for your retirement income needs, but there are good reasons to include them, and they come down to tax.
Tax relief on contributions. HMRC allows us to claim income tax relief on our pension contributions at our highest marginal rate — up to 45%. Depending on the level of income tax you pay, this means it can cost as little as £55 to benefit from a total pension contribution of £100. That is in contrast to other forms of retirement planning, such as direct investments in shares or property, where tax relief is not available.
Tax-efficient growth. On top of the relief, there is no liability for you to pay income tax or capital gains tax on the growth within your pension fund.
Tax-free cash. In addition, you can draw up to 25% of the total value of your pension fund without liability to income tax. This can subsequently be invested into tax efficient investments to generate tax-free growth and/or income as well as being sheltered from inheritance tax.
Four ways to boost your pension income
01
Contribute via Salary Exchange
If your pension is set up via your employer, or your own limited company, it can be possible to contribute via Salary Exchange. As well as tax relief on your contributions, you benefit from National Insurance savings — which increases the size of the contribution, at no additional cost to you.
02
Make additional lump-sum contributions
Other than for very high earners, we're entitled to claim tax relief on contributions up to 100% of earnings, subject to an annual maximum of £60,000. In addition, unused allowances from the previous three years can also be carried forward.
03
Optimise your fund performance
Being invested in the right funds is vital to achieving your retirement objectives. Many people never receive expert investment advice on their pension fund choices and therefore run the risk of holding the wrong funds. Assessing your appetite for growth and security, and your tolerance for volatility, is where that starts.
04
Review your contract charges and terms
Many older style pensions carry an outdated charging structure — and the more you pay in charges, the less your fund will grow. Older contracts can also be limited in flexibility: they may not offer Flexi-Access Drawdown, which allows you to vary your income and draw lump sums to suit your changing circumstances and needs over time.
Other tax-efficient ways to fund retirement
Depending on your circumstances and needs, these can be considered alongside your pension.
Tax treatment is subject to change and depends on individual circumstances. Venture Capital Trusts are higher risk and are not suitable for everyone.
The effect of compound interest
Compound interest describes how money grows on a cumulative basis over time: we don't just earn interest on the initial deposit, but also on the interest earned in previous years. Over the medium to long term the effect is significant — on a £100,000 deposit, the difference between 2% and 6% over thirty years is nearly £400,000.
Based on a £100,000 deposit. Figures are for illustration purposes only.
Investing for growth and security
Being invested in the right funds is vitally important to achieving growth and security. Many people do not receive expert investment advice, and therefore run the risk of not being invested in the most appropriate funds. Assessing your attitude towards investing — your appetite for growth and security as well as your tolerance for risk — is key to making the right decisions.
Some investments provide income tax relief on the amount invested. Others provide tax-free growth, a tax-free income, or both. This is in contrast to savings accounts and direct investments such as shares or property, where tax relief is not available. The more tax-efficient your investments are, the more quickly they will grow.
Tax-efficient investment solutions
VCTs and EIS are high risk investments and are therefore not for everyone. They invest in small to medium sized, early-stage businesses that have high growth potential, but also the potential for losses to be made.
Reviewing your existing investments
Fund selection and performance
To ensure you are invested in the right funds for you, in order to optimise growth and security.
Tax efficiency
To ensure you are benefitting from all the tax breaks available, so your money can grow faster.
Contract charges
Many older style investment contracts carry an outdated charging structure that is not competitive in the modern world of investments. The more you pay in charges, the less your fund will grow.
About inheritance tax
Inheritance tax is a tax on the total value of our estate upon death, including property, pensions, savings, investments and other assets. There is no inheritance tax liability between spouses, which means it only becomes due when the surviving spouse passes away.
Tax is only payable on estates with a value above the inheritance tax threshold. That threshold is subject to personal circumstances, and typically includes two elements:
£325,000
The Nil Rate Band
Set to remain fixed at this level until April 2028.
£175,000
The Residence Nil Rate Band
For those who own their main residence and will pass it on to children or grandchildren.
For married couples, the surviving spouse can inherit their spouse's Nil Rate Bands, effectively doubling their total threshold to a maximum of £1m. Any excess above the threshold will be liable to inheritance tax, currently at a rate of 40%.
Six ways to reduce your exposure
Ideally, each option should be explored, along with expert advice, to help you make fully informed decisions.
The use of trusts
Trusts have been in existence for many centuries. They are a means of protecting assets from inheritance tax, as well as from creditors in the event of bankruptcy and beneficiaries in the event of divorce. Once assets have been held in trust for a period of seven years, they are deemed to be outside of the settlor's estate, and therefore no longer subject to inheritance tax.
A popular misconception with a Gift Trust is that the settlor can continue to benefit from the trust's assets. HMRC would deem this a 'Gift with Reservation', meaning the assets would be included within the overall estate on death — and the trust would have failed to achieve its purpose.
Investment bonds placed within a trust are treated differently. They are not deemed a 'Gift with Reservation', despite the fact that investors can retain access to their capital and take regular withdrawals. A Reversionary Interest Trust, for example, allows withdrawals of up to 10% a year on predetermined dates — and any withdrawals deferred and not taken also fall outside the estate.
Case study
A £128,000 tax bill, and what we did about it
Colin and Carol are married, retired and in their early 70s, with an estate of £1.33m. Of that, £320,000 sat in cash, ISAs and shares, unsheltered from inheritance tax — leaving their son a £128,000 bill. They wanted to reduce it without losing access to their money.
After advice, they kept £100,000 as an emergency fund and re-allocated £220,000 into an investment bond within a Reversionary Interest Trust. After seven years those funds sit outside the estate — and if circumstances change, they can still draw on them.
The above example is for illustration purposes only. Tax treatment is subject to change and personal circumstances. Before deciding on any course of action we recommend seeking independent financial advice.
Why reviewing your pensions matters
Most of us have accumulated several different pensions during our working lives. Often these get put to one side, or forgotten about, until we get closer to retirement age.
Unfortunately, many older style pensions are out-dated and no longer fit for purpose. This can result in being invested in underperforming funds, paying more than you need to in charges and being restricted in terms of how you can access your pension income.
If left unchecked, over time this can become detrimental to the level of income you'll receive in retirement. My independent pensions review service is designed to uncover these inefficiencies and put you back in control.
The review identifies opportunities to
Provided on a transparent fixed fee basis, subject to the required scope of work, to be discussed and agreed in advance.
No cost, no obligation
Complimentary discussion
To help us both understand whether an independent pensions review may be beneficial for you, I offer a free, no-obligation exploratory discussion.
Available on request
Maximising Your Retirement Income
This guide explores the Pension Review Service and the benefits it provides in more detail.
Insights
Guides, case studies and client material
Practical guides on pensions, investments and inheritance tax, written for clients and anyone weighing up their options. Each one is available on request: leave your name, email and telephone number and the PDF opens straight away.
Our advice fees
No fees unless the advice adds real value
Everything is discussed and agreed in advance, in line with FCA guidelines and Consumer Duty.
Free consultation
We offer a free consultation in order to:
Regulated advice fees
Our regulated advice fees are based on the guidelines laid down by the FCA and in accordance with 'Consumer Duty'. This specifies that they must represent good value for money and that all clients must be treated fairly and in the same manner when it comes to charging fees.
The amount of any fees will be subject to the nature of the review and the agreed scope of work. For your peace of mind however, we would discuss and agree this in advance of any work commencing.
Importantly, our fees would only become payable if we both agree that my recommendations are in your best interest — i.e. we can demonstrate that we can add real financial value to you, and you subsequently ask me to implement them on your behalf.
Testimonials
What our clients say
{{ q.title }}
{{ q.body }}
Contact
Let's have a conversation
If you'd like some help with your financial planning, please get in touch for an initial discussion. There is no charge and no obligation.
Thank you — message received
I'll be in touch shortly to arrange a convenient time to speak. If it's urgent, please call 01245 526328.
Office-based meetings available at
Chelmsford
Elizabeth House
28 Baddow Road
Chelmsford
Essex, CM2 0DG
Bishop's Stortford
Thremhall Park
Start Hill
Bishop's Stortford
Hertfordshire, CM22 7WE
London
167-169 Great Portland Street
London
W1W 5PF
FAQs
Questions people ask before we speak
What does independent actually mean?
It means I don't work for any product provider or institution. Recommendations are based on a comprehensive and fair analysis of the whole market, and I work solely for my clients and in their best interests.
What happens at the first meeting?
It's a free consultation. We get an understanding of your situation and objectives, I answer your questions, we discuss how I can potentially help, and we both decide whether we want to explore working together. There's no charge and no obligation.
When would I have to pay a fee?
Only if we both agree the recommendations are in your best interest, and you then ask me to implement them. Any fee is discussed and agreed in advance of work commencing. See our advice fees.
Do I need a minimum amount invested?
No. What matters is whether advice can add real financial value in your circumstances — that's what the initial conversation establishes.
How is my money protected?
Advice is given as an Appointed Representative of New Leaf Distribution Ltd, authorised and regulated by the FCA. The advice is fully guaranteed by New Leaf, and backed by professional indemnity insurance with a maximum claims limit of £2m per claim. You also have recourse to the Financial Ombudsman Service and the Financial Services Compensation Scheme.
Can we meet in person?
Yes. Office-based meetings are available in Chelmsford, Bishop's Stortford and London. Alternatively, if you'd prefer a home visit, I'll be pleased to come to you. I'm equally happy to speak by phone or video call.
Legal
Privacy Policy & Terms
Online Privacy Statement
Who are we?
We are Castle Financial Planning and appointed representative of New Leaf Distribution Ltd.
Castle Financial Planning provides financial planning solutions and advice through experienced and qualified advisers based in the UK.
Currently Castle Financial Planning and New Leaf Distribution jointly determine the purposes and means of processing personal client data relating to giving advice. This means we are joint data controllers for these core advice giving activities and therefore responsible for managing this client data and ensuring compliance.
However, Castle Financial Planning is solely responsible for some activities, for example any direct marketing that we undertake.
What is this privacy statement about?
To supply our customers with our services we need to use information about you, and some of that may be personal or private. For example we may need to know your name and address, details of how you would like to be contacted (e.g. your mobile phone number), or how you would like to pay for the services we provide you.
As we do this, we’d like you to take some time to read this privacy statement. It will explain what information we might collect about you, why we collect it, what we may use it for, and who we may give it to. We’ll also explain your rights towards your information and how we look after it while we have it.
What information do we collect about you?
The information we collect about you may vary based on what service we provide to you. Typically, we need details like:
- Your name and address so we know who you are and what services you need from us
- Your contact details like phone number or email so that we can keep in touch with you about our services.
- Your bank account or other financial details so we can manage your payment for our services.
If you are receiving some financial services advice, we will need to know more information about your current position. This might include information regarding:
- Your employment information
- Your assets and liabilities
Some financial services products may require us to collect information about your health and lifestyle.
We only collect information about you that we need to make sure you get the best service from us. We respect your privacy and we try to minimise what we do collect.
How do we collect information about you?
We prefer to collect the information we need directly from you. That way, you know what we have, and we can be sure you’ve provided us with the most accurate and up to date information.
We will usually do this:
- When you complete our fact find and discussion document.
- When you contact us for any reason.
- If you complete an online form.
- If you complete a survey.
- When completing application forms.
What do we do with the information we collect about you?
We use your information in various ways, such as to:
- Meet the purposes that you provided your information for
- Provide you with the services you want
- Let you know about goods or services we feel would be beneficial to you.
- Prevent fraud, money laundering and financial crime
- To confirm your identity.
- Credit scoring and assessment, and credit management (where applicable).
- Keep our records accurate and up to date.
- Comply with any legal or regulatory obligations we may have.
Who do we share your information with?
We appreciate that you have provided your information to us and may not want us to share it with other people or organisations, however sometimes it is necessary for us to do so.
We only share your information where we are permitted or required to by law, or where you have requested us to do so. We may share your information with, for example:
- Any of your family, associates, or someone who represents you, where you have asked us to do so.
- Our employees who provide you with our services.
- Carefully selected organisations and specialists to help us provide you with our services.
- Credit reference and fraud prevention agencies in order to help prevent and detect fraud as part of our due diligence process.
- Any person, organisation or regulator where we are required to because of a court order, regulatory responsibility, legal duty or statutory obligation.
- We are careful to minimise such sharing.
Although we are a UK business, we may sometimes share your information with an organisation who is outside the UK. Such companies may also be outside of Europe. We may do this, but we will only do so where we are permitted to by law.
Whenever we share your information we do everything we can to make sure it is protected from misuse or loss.
How do we look after and secure your information
When we use information about you, we take all reasonable efforts to do so fairly and lawfully.
We think it likely that our customers know we use information about them, and we provide notices of such wherever we can.
We never use information about you unless it is lawful for us to do so and we have a clearly defined need or purpose.
When we collect information about you we ensure that we minimise what we collect. We try not to keep your information for longer than we need it and we ensure that the records we have about you are managed properly and deleted promptly and securely when we no longer need them.
We make every effort to ensure your rights towards your information, which we detail below.
We take appropriate care to secure the information we hold about you. We have robust technical security such as passwords and information encryption. We also have policies and procedures to ensure your information is only available to our employees who need to see it to do their job, and we train those employees appropriately.
Also, we establish robust procedures and contracts to extend these protections to any other person or organisation we may need to give your information to.
In everything we do with your information we try to be fair, lawful, and open, and we take seriously our obligations towards your privacy and the protection of information we may hold about you.
What are ‘Cookies’ and how does Castle Financial Planning use them?
A cookie is a piece of information that is stored on your computer’s hard drive by your Web browser. On visiting the Web Site, your computer server will use the cookie to guarantee a secure connection. Most browsers accept cookies automatically, but usually you can alter the settings of your browser to prevent automatic acceptance. If you choose not to receive cookies, you may not be able to use certain features of this Web Site.
Castle Financial Planning may conduct analyses of user traffic. These analyses will be performed through the use of IP addresses and cookies which are required to ensure a secure server connection. Castle Financial Planning does not use cookies to store any personal data or browsing habits.
Third parties such as advertising agencies and content providers may use cookies on this Web Site to collect personal information about you. Castle Financial Planning recommends that you read the privacy statement of any third party before using their web site. Castle Financial Planning is not responsible for the use of such cookies or any other ways in which your personal data may be collected or used by such third parties.
Other information regarding our Website
Certain areas of our websites use a Secure Socket Layer (SSL). A SSL is a security device which ensures that any data which you enter is encrypted during transmission over the internet. Encryption means the data is encoded so that it is not legible until such time as we decode it.
No data transmission over the internet can ever be entirely secure. While we do our best to protect your personal information, we cannot guarantee its security and you must be aware of this when using our websites.
Our websites may contain links to other websites. If you follow a link to any of these websites, please not that these websites have their own Terms & Conditions and privacy policies and that we cannot accept responsibility for their content. This privacy statement applies only to our website.
By email and phone
If you have contacted us by email, or provided an email address, we may use that to contact you if we need to.
You should also be aware that information conveyed by email could be deliberately or accidentally intercepted or corrupted.
Whilst we make every effort to ensure that emails we send to you are free from viruses this cannot be guaranteed. We recommend that you scan all email for viruses with appropriate and frequently updated virus checking software. You should also avoid sending us emails from unsecure or public wi-fi zones (such as coffee shops) to mitigate your messages being intercepted.
If you have given us you phone number (landline or mobile), we may use it to contact you if we need to, including sending texts.
Please let us know if your mobile phone number or email address changes so that we can keep this information up to date.
Your rights
GDPR gives you certain rights towards your personal information. We take all reasonable efforts to ensure we allow you to exercise those rights.
You have the right to see all the personal information we hold about you.
We’ll handle routine enquiries as part of our usual customer service. If you want to see more of the information that we have about you, you can make a data subject access request. You can contact us by e-mail: info@castlefinancialplanning.co.uk or by telephone: 01245 526328
To ensure that we only give your information out to you and not someone else, you will need to provide us with two current forms of identification.
Once we receive your written request, any clarifications, identification, we respond as soon as we can within 1 calendar month.
You have the right to stop us causing you ‘damage or distress’
Unless you have consented to us using your information, or have a contract with us, or we are acting to comply with a legal obligation or in a life or death situation, you can object to us using your personal information in a way that causes you ‘substantial and unwarranted damage or distress’.
Damage means that we will use or have used your information in a way that caused you some loss or harm which we shouldn’t have.
Distress means that we will use or have used your information in a way that caused you some upset or anguish which was more than an annoyance.
You can write to us and ask us to stop using your information in that way. We will respond within 21 days.
You have the right to have your information corrected
We take all reasonable steps to ensure that the information we have about you is accurate and up to date.
If you think that what we have is not accurate or up to date, please tell us as soon as possible and we will ensure it is corrected.
You have the right to stop us direct marketing to you
If you have received financial advice from one of our advisers, we would like to keep you notified of products and services that we feel might be beneficial to you as part of our ongoing service to you. This could extend to contacting you in advance of a product deal expiring or to keep in touch for a yearly review.
You have the right to opt out of marketing information and tell us what your communication preferences are by contacting us at the number or address provided below. You may opt out at any time if you don’t want to receive any further communications of this nature.
Every time we contact you about such offers, we will give you the opportunity not to hear about anymore.
If you don’t want to receive such offers at all, please let us know by e-mailing info@castlefinancialplanning.co.uk or by calling 01245 526328.
Also, we will not send you these offers by phone if you have registered with the Telephone Preference Service or by mail if you have registered with the Mailing Preference Service.
Please note though, that you may still receive non-personalised marketing material through your letterbox.
Castle Financial Planning, New Leaf Distribution and data protection
The General Data Protection Regulation governs how we may use your personal information. We are registered under the Act and regulated by the Information Commissioner’s Office (ICO).
You can find our registration details here: Castle Financial Planning Registration Number: ZB691298
New Leaf Distribution Ltd (Registration Number: Z966060)
You can also find a lot more information about this on the ICO Website or by contacting them at:
Information Commissioner′s Office
Wycliffe House
Water Lane
Wilmslow
Cheshire
SK9 5AF
(Tel: 01625 545 700)
Changes to this statement
From time to time, we may amend this privacy statement to reflect changes in the law, guidance from the Information Commissioners Office (ICO), our experience of handling your information, or for other legitimate reasons. We will do this by posting the amended privacy statement on our website. We therefore suggest you check our online privacy statement from time to time to make sure you are aware of the latest version.
Legal
Complaints Procedure
As an Appointed Representative of New Leaf Distribution Limited, I aim to provide you with a high standard of service. If you are unhappy with any aspect of our service, please get in touch:
- Email: complaints@newleafgroup.co.uk
- Write to: New Leaf Distribution Ltd, 165 – 167 High Street, Rayleigh, Essex SS6 7QA
- Call: 01702 431130
We will acknowledge your complaint promptly and aim to resolve it within 8 weeks.
If you remain dissatisfied, you have the right to refer your complaint to the Financial Ombudsman Service (FOS):
- Website: www.financial-ombudsman.org.uk
- Phone: 0800 023 4567
- Address: Financial Ombudsman Service, Exchange Tower, London, E14 9SR
About us
Our history
Thirty years of advice, and one decision that shaped everything after it: to work for clients, not institutions.
I've been a financial adviser for more than 30 years, and have helped many individuals, families and business owners to successfully manage their finances. Much of that career was spent inside some of the UK's largest financial service companies — good training, and a close view of how advice works when it sits within a large institution.
I formed my own practice in order to focus on one thing: helping my clients achieve their financial goals. Being independent means I don't work for any other institution. I work solely for my clients and in their best interests, with access to the whole marketplace, so I can recommend the most suitable product or service for your circumstances and needs.
Career begins in financial services
Working for some of the UK's largest financial service companies.
Appointed Representative of New Leaf Distribution Ltd
Advice fully guaranteed, and backed by professional indemnity insurance of up to £2m per claim.
Castle Financial Planning is founded
An independent practice, formed to put clients' interests first and foremost.
One totally independent adviser, covering three office locations
Client meetings held in Chelmsford, Bishop's Stortford and London — and the same person from first call to annual review.
About us
Our values
Five commitments that decide how advice is given here, and what happens when it isn't needed.
Independence
I don't work for any institution. Recommendations follow a comprehensive and fair analysis of the whole market, which means the answer is whatever suits you — not whatever is available on a panel.
Clarity
My role is to make the complex simple. Clear, prompt communication without jargon, so you can make fully informed decisions and plan ahead with confidence.
Value for money
Fees are agreed in advance and only become payable if we both agree the recommendations are in your best interest. Only cost-effective products and services get recommended.
Care
In keeping with the FCA's Consumer Duty: understand what matters to you, prevent foreseeable harm, and make sure your experience is a first-class one throughout.
Accountability
The advice is fully guaranteed by New Leaf Distribution Ltd and backed by £2m of professional indemnity cover per claim. I also ask for your feedback, and act on it.
Worth a conversation?
The first discussion is free, and there is no obligation on either side.
Get in touch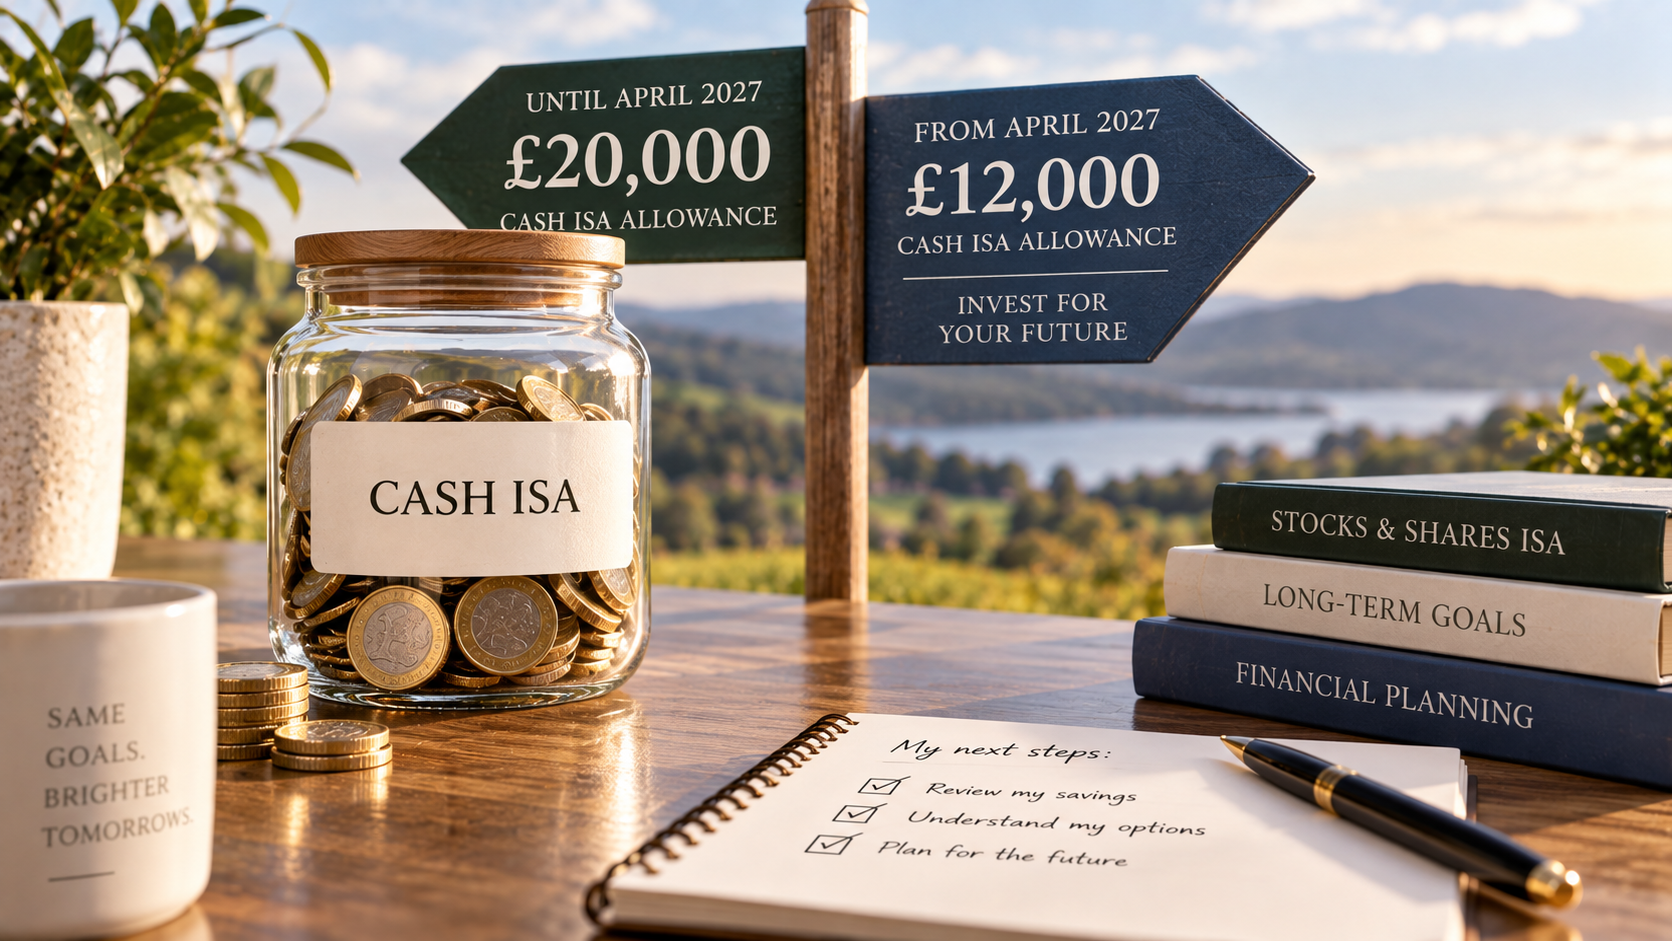 Savings & ISAs
Cash ISA Allowance Is Shrinking From 2027. Here's What to Know
From April 2027 the cash ISA allowance falls from £20,000 to £12,000 for under-65s. What's changing, and what to do with the time before it lands.
Read the article →
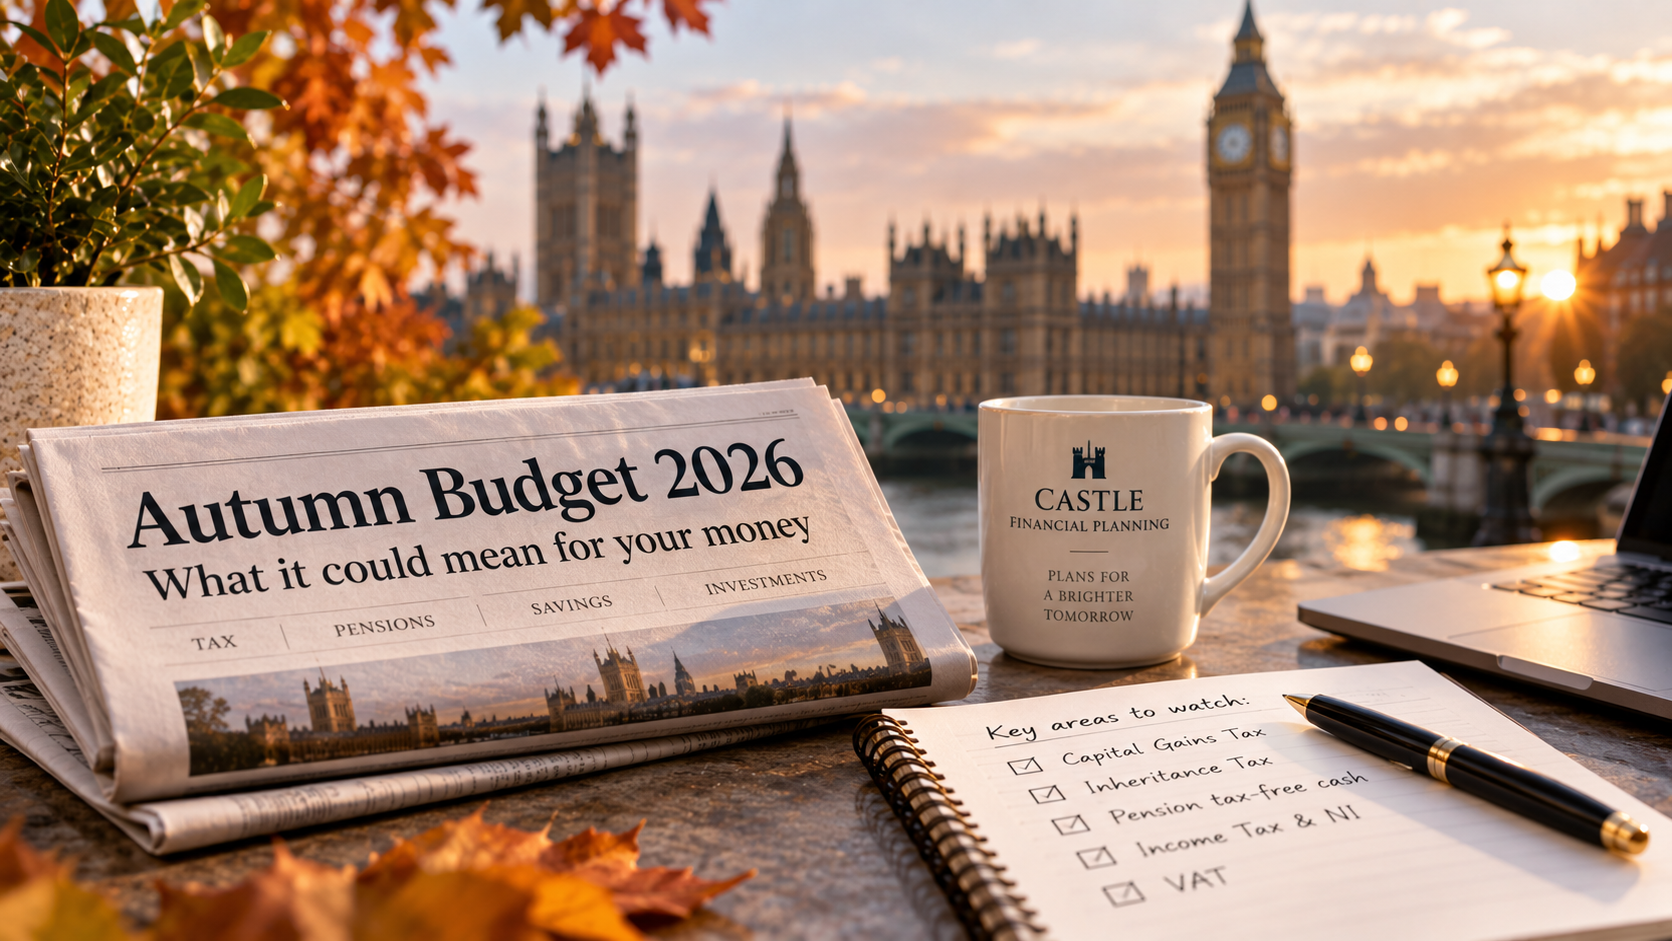 Tax
Autumn Budget 2026: What Could Change for Your Money
The Chancellor delivers the Budget on 28 October. What is being discussed, what is already law, and why guessing is a poor strategy.
Read the article →
 Pensions & IHT
Pensions Are Losing Their Inheritance Tax Protection From 2027
Unused pension funds will count towards your estate from April 2027. What it means for your family, and what to look at now.
Read the article →
Legal
Cookie Policy
What cookies are
Cookies are small text files placed on your device when you visit a website. They allow the site to function properly, and to remember choices you have made. Some cookies are essential; others help us understand how the site is being used.
The cookies we use
Managing your preferences
You can change your mind at any time. Use the button below to reopen the cookie banner, or clear cookies through your browser settings.
More information
For how we handle the personal data you give us, see our privacy policy. Questions about either can be sent to john@castlefinancialplanning.co.uk.
If you're under 65 and use a cash ISA to save, a change is coming that's worth planning around now. From 6 April 2027, the amount you can pay into a cash ISA each year is being cut from £20,000 to £12,000.
This isn't a rumour or a prediction. It's a confirmed change, and it will affect how a lot of people manage their savings.
What's Changing
Here's the change in plain terms:
None of this affects money you've already saved. It only applies to new money you pay in from April 2027 onwards.
Why the Government Is Doing This
The thinking behind the change is to nudge people away from holding large amounts of cash and towards investing more of their long-term savings instead. Whether that's the right move for you depends entirely on your own circumstances, how much risk you're comfortable with, and what you're saving for.
What This Means for You
If most of your savings sit in a cash ISA, this change is worth thinking about now rather than waiting until 2027.
You've got until April 2027 to use the full £20,000 cash ISA allowance. For the current tax year, and the one after it, you can still put the whole £20,000 into cash if that suits you.
You may need a stocks and shares ISA for the first time. If you want to keep saving £20,000 a year in an ISA after 2027, some of that will need to go into investments rather than cash. That's a bigger decision than it sounds, and it's worth getting advice before you make it.
Your goals should drive the decision, not the deadline. Cash makes sense for money you need soon, or for an emergency fund. Investing makes more sense for money you won't need for several years. The changing allowance is a good reason to check you're using the right type of savings for each of your goals, not just to shift money around for the sake of it.
Make the Most of the Time You Have
There's a window now, before April 2027, to review how your savings are set up and make sure you're getting the most from your allowance while the higher cash limit is still available.
John Castle has been helping people in Essex and Hertfordshire manage their savings and investments for over 25 years. As an independent adviser, he can look at your full financial picture and help you decide how much to hold in cash, how much to invest, and how to make the change to the ISA rules work in your favour rather than against you.
Contact Castle Financial Planning to talk through your savings and investment plan before the 2027 changes land.
The Chancellor will deliver the Autumn Budget on 28 October 2026. Every year, the run-up to the Budget brings a wave of headlines guessing what might happen to tax and pensions. This year is no different, and some of what's being talked about could genuinely affect your finances.
Nothing is confirmed until the Chancellor stands up in Parliament. But it's worth knowing what's being discussed, so you're not caught off guard.
What's Being Talked About
A few areas keep coming up in the speculation:
Capital Gains Tax. There's talk of bringing Capital Gains Tax more in line with how income is taxed. If you hold investments outside a pension or ISA, this is worth keeping an eye on.
Inheritance Tax. IHT is a regular target for Budget speculation, and this year is no exception. Some commentators have raised the idea of reforming how relief works for inherited assets, including a possible change to how the value of inherited shares and property is calculated for tax purposes.
Pension tax-free cash. Every year brings rumours that the 25% tax-free lump sum from pensions could be reduced or capped. It hasn't happened yet, and there's no confirmation it will this year either. But if you're close to retirement, it's still worth understanding your options.
Income Tax, National Insurance and VAT. The government has said it doesn't plan to raise the main rates of these taxes. Tax thresholds, however, are already frozen until April 2031, which quietly pulls more people into higher tax bands each year as wages rise.
What's Already Locked In, Whatever the Budget Says
Some changes don't depend on this Budget at all, because they're already law:
These are worth building into your plans now, separately from whatever the Budget brings.
Why Guessing Is a Bad Strategy
It's tempting to make big financial decisions based on Budget rumours, like rushing to withdraw pension cash or sell investments before a change that might not even happen. This has caught people out before. Reacting to speculation, rather than confirmed rules, can leave you worse off than if you'd simply waited and planned properly.
The better approach is to understand your current position clearly, know which changes are already confirmed, and be ready to adjust once the real announcements are made.
Get Ready, Not Rushed
You don't need to make any decisions based on guesswork. What you do need is a financial plan that can flex as the rules change, built by someone who understands your full situation.
John Castle has guided clients through Budget after Budget for more than 30 years. As an independent adviser working across Chelmsford and Bishop's Stortford, he'll help you separate the real changes from the noise, and make sure your plan holds up whatever the Chancellor announces.
Get in touch with Castle Financial Planning to talk through what the Autumn Budget could mean for you.
For years, your pension has been one of the best ways to pass money on to your family without the taxman taking a cut. That's about to change.
From 6 April 2027, most unused pension funds will be counted as part of your estate for Inheritance Tax purposes. If you've been saving into your pension partly as a way to leave money to your children or grandchildren, this news matters to you.
What's Actually Changing?
Right now, if you die with money still sitting in your pension, it usually passes to your loved ones free of Inheritance Tax. That's why many people have left their pension untouched for as long as possible, using other savings to live on instead.
From April 2027, that will no longer be the case for most people. Unused pension funds and death benefits will be added to the value of your estate. If your total estate goes over the Inheritance Tax threshold, your family could face a 40% tax bill on the money above it.
There is some good news. If you die before age 75, your pension can often still be passed on income-tax-free, as long as it's paid out within two years. Die after 75, and whoever inherits your pension will usually pay income tax on it at their own rate, on top of any Inheritance Tax due on the estate.
Why This Matters Now, Not Later
April 2027 might feel a long way off, but the decisions that shape your estate take time to put in place. If your financial plan has been built around leaving your pension to your family tax-free, that plan needs a second look.
This could affect you if:
None of this means you should panic or make rushed decisions. But it does mean now is a sensible time to sit down and work out what your estate will actually look like under the new rules, and what you might want to do differently.
What You Can Do About It
Every family's situation is different, so there's no single answer that works for everyone. But there are options worth exploring, such as:
This is exactly the kind of change where good advice pays for itself. Getting it wrong, or doing nothing, could mean your family pays tax that could have been avoided with the right planning.
Talk to Castle Financial Planning
John Castle has spent more than 30 years helping people to make sense of changes like this. As an independent adviser, he'll look at your whole financial picture, not just your pension, and help you build a plan that still works under the new rules.
If you're worried about how the 2027 pension changes might affect your family, get in touch for an initial conversation. There's no pressure, just clear advice about where you stand and what your options are.
Contact Castle Financial Planning or explore our Pension Review Service.
Thank you
Thank you for your request
Thank you for getting in touch
We've received your request for {{ thanksDocName }}. John will email a copy to you shortly.
We've received your request. John will email a copy to you shortly.
Your message has been sent. John will be in touch with you shortly to arrange an initial discussion.
If you'd prefer to speak to us now, call 01245 526328 or email john@castlefinancialplanning.co.uk.